

Builders Fintech Funding Index: 237 (last full week, week of 28 Sep). 31 equity rounds recorded, against a 12-week average of 13. Median disclosed USD round: index 86. Our round coverage expanded in September 2026, so the Index overstates activity until mid-December. Full reading
GCash parent Mynt priced the largest IPO in Philippine history at P6.60 a share, raising about P53B, Capitolis raised $220M including a $120M Series E led by Citi at a $1.9B valuation, and Revolut ’s Nik Storonsky said a US primary listing “was always the target”. Below: McKinsey & Company ’s preview of its Global Banking Annual Review 2026 (record $1.3T net income, fintechs at 17% of comparable revenue, no grace period on AI), the week’s rounds and funds, and three managers raising now.
Builders in Fintech: No episode released this week, but you can always recover the last one with Nika Kurdiani, CEO of TBC Uzbekistan.
All episodes: YouTube · Spotify · Apple Podcasts · Amazon. Founders and VCs who want to come on the show: message me on LinkedIn.
This was also Fintech Meetup Europe week! I had a great time in Lisbona, meeting with some very interesting fintech companies and investors.
The report: banks had their best year, and the least time
McKinsey & Company, Global Banking Annual Review 2026: Precision with speed. A preview of the October report: 2025 results, a new regional map of banking models, the four forces eroding banks’ hold on the customer, and why AI leaves no grace period this time. Here my main takeaways:
The numbers. Global banking net income reached $1.3T in 2025, up 7% on a record 2024 and again the most of any industry. Revenues before risk costs rose from $6.1T to $6.4T; balances held by banks (deposits, loans and AUM) from $381T to $406T, growing 6.5% against 6.2% a year in 2020–24. Net interest margin slipped from 1.65% to 1.63% globally, with US (+9 bps), Japan (+7) and UK (+6) banks the exceptions and Brazil the outlier (3.55% to 2.93%). Cost-to-asset ratio improved from 1.31% to 1.23%. Banks generated another $853B of surplus free cash flow to equity. The yellow lights: return on tangible equity fell from 12.4% to 11.8%, against 20% in 2003–07, and banking still has the lowest P/B and P/E of any industry.
Where the money sits. Funds intermediated by the financial system grew by $131T to $468T between 2020 and 2025, with private capital the fastest category at 14.1% a year. The share held on bank balance sheets fell from 44% in 2022 to 40% in 2025: transaction banking and distribution now bring 47% of revenues and 57% of profits, the balance sheet 53% and 43%. North American intermediated funds grew 8% from 2022 to 2025, Europe’s at half that rate, despite a US gross savings rate of 18% against 25% in the EU. US bank ROE reached 12%; European banks improved from 10.7% to 11.6%, mostly through operating performance.
Six regional models. McKinsey plots banks by disintermediation (off-balance-sheet share) and cost efficiency. North America sits at 64% disintermediation with a 2.1% cost-to-asset ratio; Western Europe, Australia and New Zealand at 49% and 1.2%; East Asia at 38% and 0.7%; Latin America at 40% and 3.3%; the Gulf at 16% and 0.9%; Southeast Europe, South Asia and Africa at 26% and 1.8%. Sweden and Finland are singled out as the best of both worlds; southern Europe relies more on the balance sheet at higher cost. Global universals fell from ten of the top 20 banks by market cap in 2005 to six in 2015 and four in 2025, replaced by continental players such as DBS, OTP and BBVA; wholesale is the only line that stays global, at about 11% of revenues.
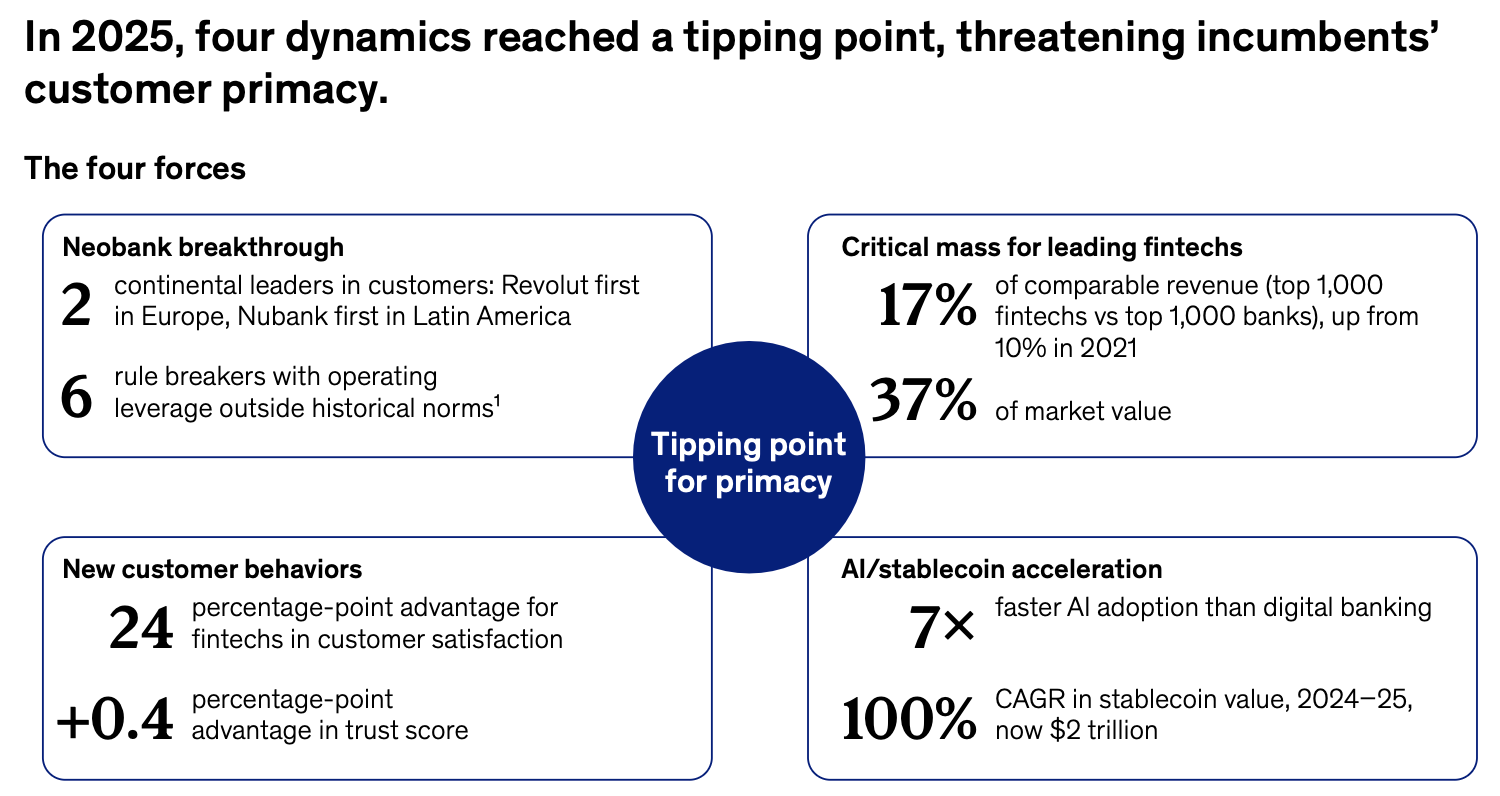
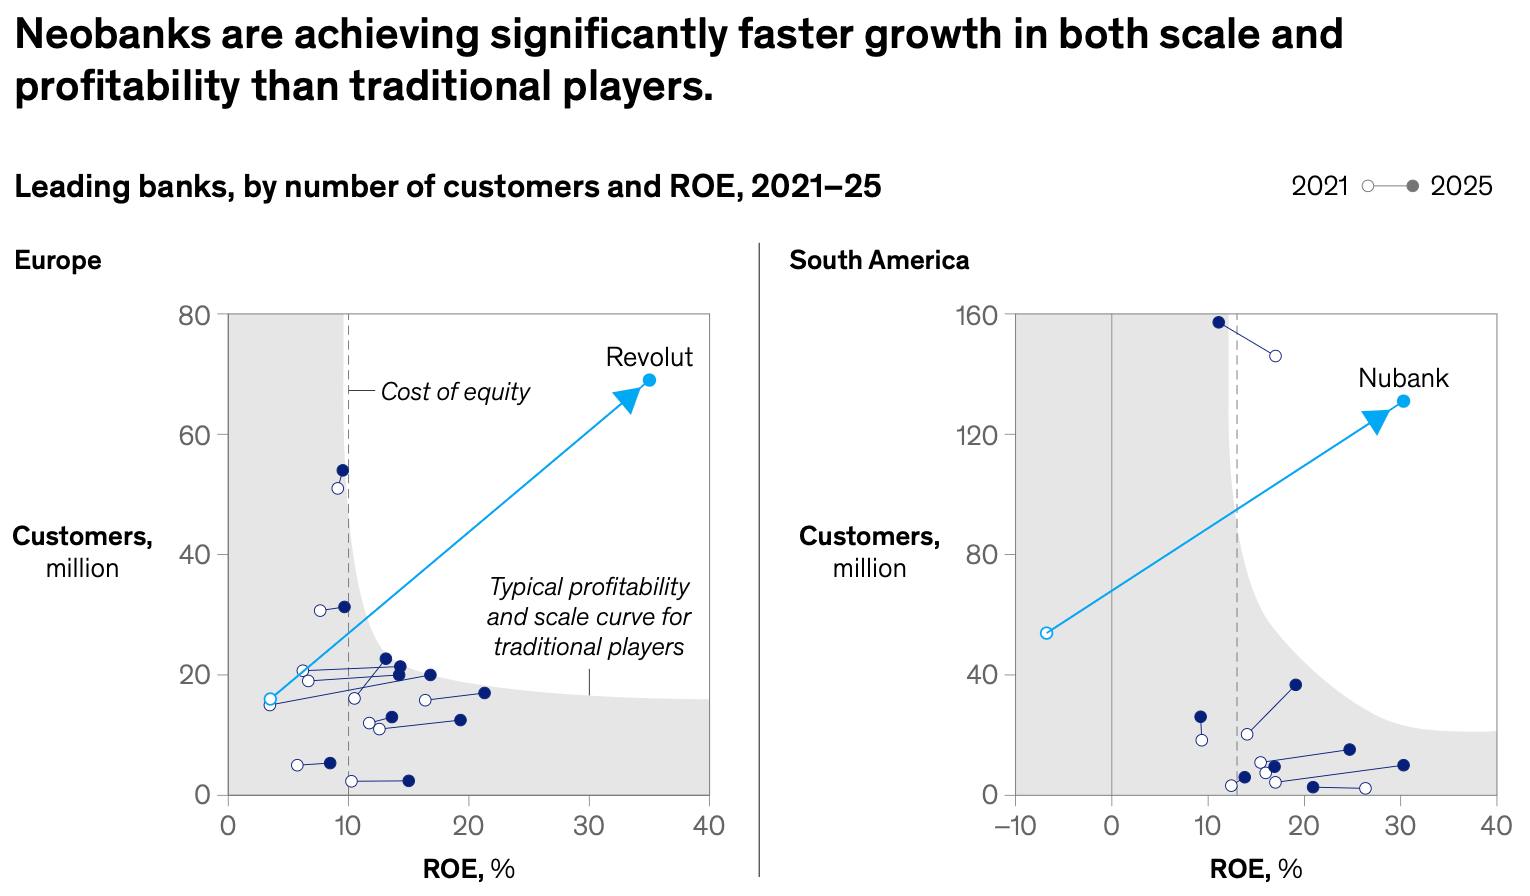
Four forces at the tipping point. Fintech revenues reached $650B against the industry’s $7.3T, but the top 1,000 fintechs grew revenues 22% a year in 2021–25 against 5% for the top 1,000 banks, lifting their share of the combined pool from 10% to 17% and holding 37% of the banks’ market capitalisation. Fintechs filed 21 US bank-licence applications in 2025, against one in 2024 and five in 2023, with about 38% accepted and approvals 40% faster. Revolut has 69M customers and is the 11th most valuable bank in Europe; Nubank has 131M and is the most valuable in Latin America; WeBank 420M. ROEs run at about 35% for Revolut and Wise, 30% for Nubank and above 20% for Robinhood, with 12,000 and 10,000 employees at Revolut and Nubank. Stablecoin circulation is still about $300B, supporting roughly $400B of payments in 2025, against forecasts of $4T by 2030. In Europe fintechs now lead banks by 24 points on net customer satisfaction (39 vs 15) and by 0.4 on trust (8.3 vs 7.9); 65% of Gen Z would try an e-wallet provider, 30% of boomers.
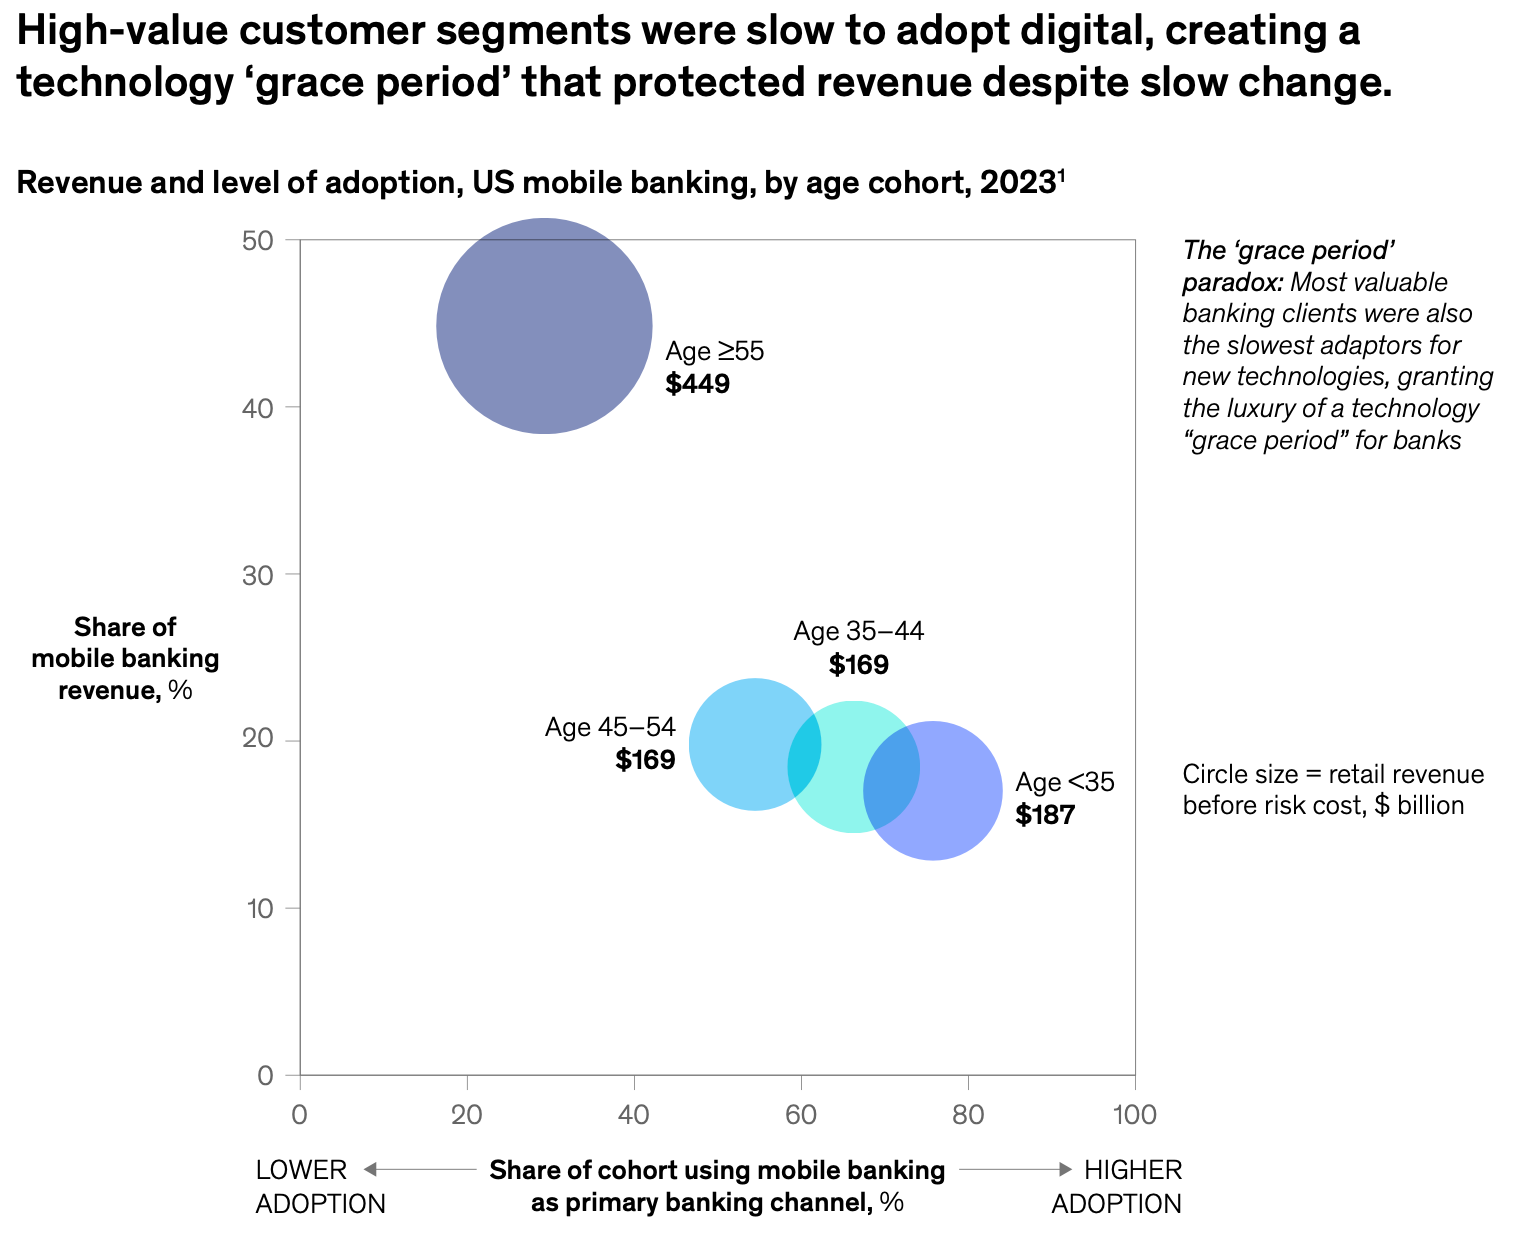
No grace period. Banks’ most valuable customers (55 and over, $449B of US retail revenue against $169–187B for each younger cohort) were the slowest to adopt mobile, which let banks follow rather than reinvent; branch networks shrank only 20–30%, and banks spend more on technology than the next four sectors combined while ranking among the worst sectors for productivity growth. Gen AI reached 45% of US working-age adults within two years of ChatGPT and 55% by 2025; digital banking took 15 years to reach the same share. Usage is 61% for Gen Z, 63% for millennials and 53% for Gen X, so the generational gap that protected banks has gone. Agentic AI can move idle deposits to higher-yield accounts, and net interest income is about 60% of retail bank revenue.
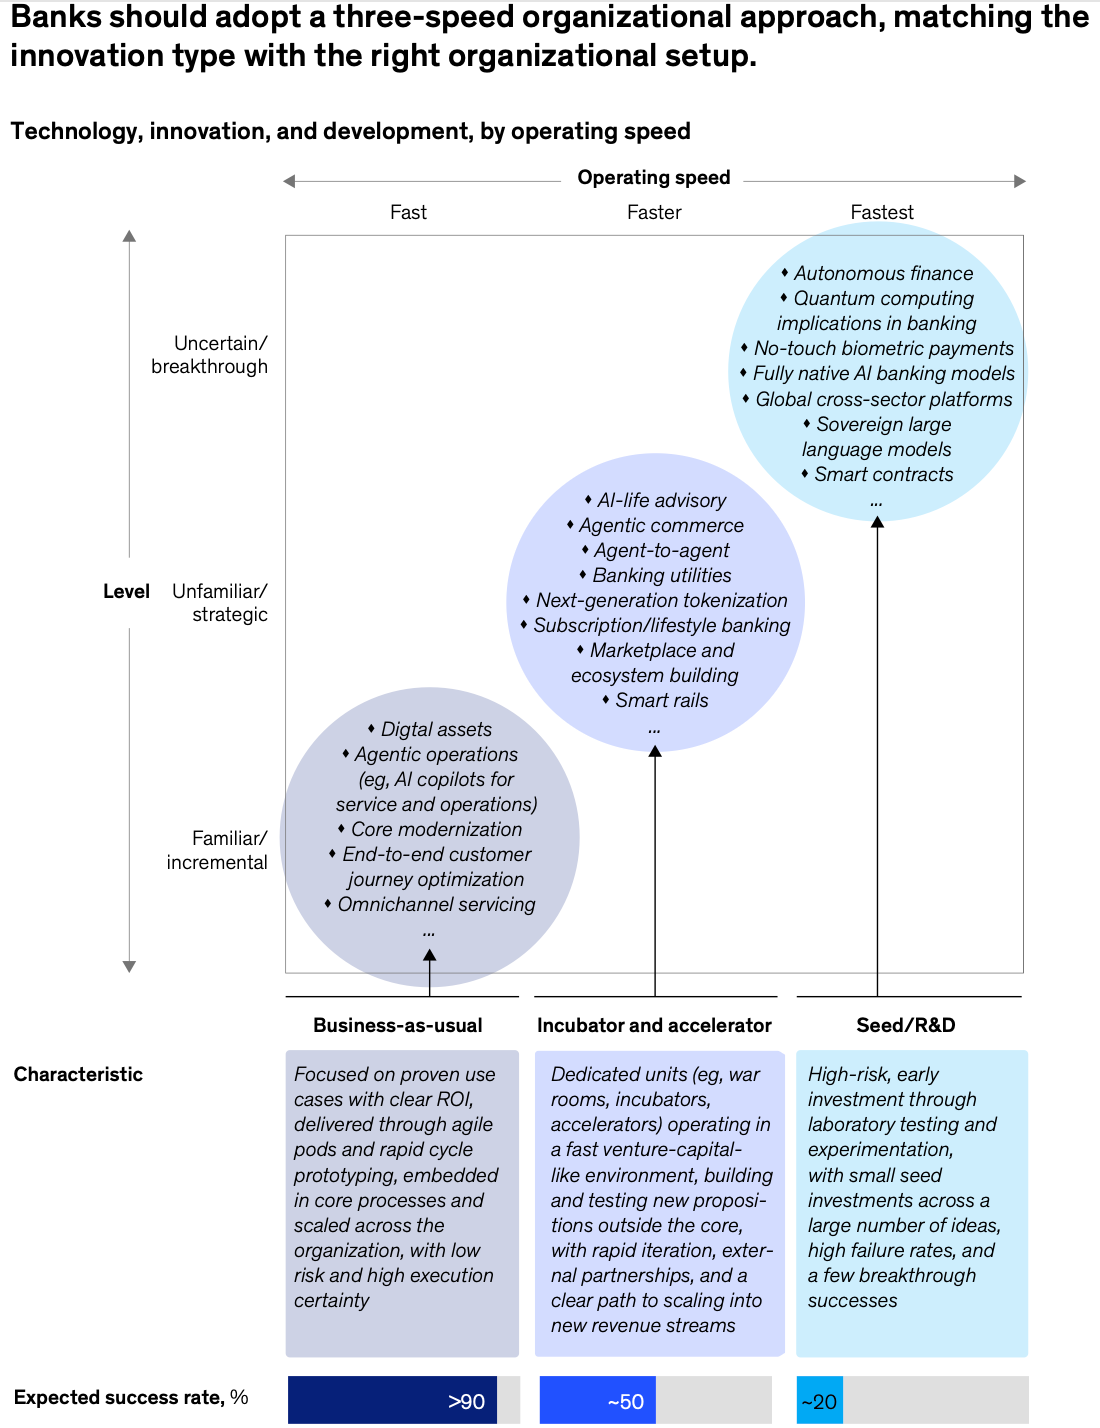
Precision with speed. The prescription is last year’s precision strategies at a new pace: real-time customer value engines (leading banks lift engagement 20–30 points and customer value 10–25%), fail-fast technology portfolios, capital reallocation toward fee and beyond-banking income, and programmatic capability deals rather than scale M&A. Innovation is skewed to the riskiest quadrant: of 3,458 ideas clustered from 300,000 products, about 70% sit in high-popularity, low-penetration areas, led by AI and digital assets. McKinsey proposes a three-speed organisation: business-as-usual with success rates above 90%, incubators at about 50%, and seed and R&D at about 20%, for autonomous finance, sovereign LLMs, smart contracts and biometric payments.
The read. The number that matters is 17%: the share of the combined revenue pool that the top 1,000 fintechs now take from the top 1,000 banks, up from 10% in four years, while investors price them at 37% of the banks’ market value. Everything else in the report explains why banks cannot wait this one out as they did mobile: the customers who stayed in the branch are now using gen AI at nearly the same rate as their children, and the products most exposed, deposits and consumer lending, are the ones agents can reprice without a branch visit. This week’s news reads the same way. Revolut, 69M customers and a 35% ROE in McKinsey’s data, has preliminary US charter approval and now a stated preference for a US primary listing; Modern Treasury and Rain filed for OCC trust charters on the same day, 21 fintech licence applications later becoming a trend; Spiko raised $90M with $2.7B in tokenised cash funds, and Samsung put USDC into the default wallet of 82M US phones. Banks are responding the way the report recommends, by buying capabilities: Grupo Cibest for PTM’s agent network, Personio for Circula, Capitolis financed by nine banks to buy eSecLending. Watch two things in the October full report: whether European banks, at 11.6% ROE and 1.2% cost-to-asset, can run a three-speed model inside a regulatory moat, and whether the fintech share of revenue keeps compounding at 22% against 5%.
The week in six stories
GCash parent Mynt prices the largest IPO in Philippine history. Reuters reports a price of P6.60 a share, below the P7–10 range floated earlier; Mynt declined to confirm. The base offer of up to 8.03B shares raises about P53B, rising to about P60.9B with the 1.2B-share overallotment, and lists on the Philippine Stock Exchange on 20 October as GCASH. Cornerstone investors including Capital Research, Citadel, Fidelity International, HSBC Global Asset Management, the IFC and Lazard committed P36.5B; GCash has 41.5M monthly active users.
Capitolis raises $220M, including a $120M Series E led by Citi at a $1.9B valuation. About $100M of debt comes from First Citizens Innovation Banking, Hercules Capital and Pinegrove; Bank of America, Nomura and Tradeweb join Barclays, BNP Paribas, J.P. Morgan, State Street and UBS as shareholders. The Series D in 2022 valued the company at $1.6B. Most of the capital funds the $200M cash acquisition of securities-lending agent eSecLending from Parthenon Capital, agreed on 29 September.
Ledgebrook raises $200M co-led by Allianz X and Rockefeller Capital Management. The Boston specialty insurer, founded in 2022 by CEO Gage Caligaris, writes liability cover for mid-sized US businesses through wholesale brokers and is on track to pass $1B of cumulative premium. Allianz Re signed a multi-year reinsurance agreement alongside the round; AM Best rated the carrier A- in August.
Valon raises a $150M Series D led by Ribbit Capital at a $2.3B valuation. Andreessen Horowitz participated; the valuation doubles from the $100M Series C of October 2024. Two of the ten largest US mortgage servicers run on ValonOS and one in six outstanding US mortgages is under contract to move onto it, including Newrez by 2027.
Spiko raises a $90M Series B led by NEA. Index Ventures, Bpifrance, White Star Capital, Blockwall and Frst followed on, taking total funding to $120M. The Paris and London company issues regulated tokenised money market funds in euros, dollars, sterling and Swiss francs; assets under management have grown from about $400M at the July 2025 Series A to $2.7B, across more than 10,000 clients in over 25 jurisdictions.
Revolut says a US primary listing “was always the target”. CEO Nik Storonsky told Bloomberg TV on 8 October that the company would favour the US for any IPO, citing liquidity, after telling Les Echos last month it was weighing a dual London–New York listing. Revolut received preliminary approval for a US national bank charter in September, is valued at $115B privately, and has said a listing is not before 2028.
Also: Settle secures a $240M credit facility for working capital lending; OKX extends its round at a flat $25B valuation with SC Ventures, Circle and Ripple; Stuut raises a $52.5M Series B led by Insight Partners; Noah closes a $38M seed for stablecoin payments; Meanwhile raises $37.5M at a $350M valuation for bitcoin-denominated life insurance; Catalyst raises a $30M seed led by Sequoia for AI trading agents; TrueLayer raises $27M led by CDP Venture Capital; Shares completes its acquisition of Treezor from Société Générale; First Digital agrees a Nasdaq SPAC at a $250M valuation; Samsung Wallet adds USDC transfers on Solana for 82M US devices.
Funds. Nine new vehicles this week, plus one LP commitment: Forbion (€2.3B across Growth Opportunities Fund IV and Ventures Fund VIII, biotech), Endeavor Catalyst ($320M Fund V, oversubscribed against a $300M target, AUM above $850M), SEVA Growth ($160M Fund II, minority growth equity in profitable founder-led software), Linse Capital ($150M Ignition strategy, $75M early-stage fund plus $75M co-investment, deep tech), Graduate Ventures (€125M second seed fund, €100M committed, Dutch tech), LAUNCHub Ventures (€65M first close of Fund III, target above €75M, pre-seed and seed in CEE and SEE), PSV Tech (€56M Fund II, pre-product-market-fit founders in the Nordics), Anorak Ventures ($35M Fund III, aerospace, defence and advanced manufacturing), Nevermind (€23.6M first close of NVM Venture Lazio, target €35M, dual-use deep tech in Italy) and British Business Bank (£10M commitment to Fuel Ventures’ funds through the Regional Angels Programme).
All rounds
Equity
Spiko — $90M Series B led by NEA, tokenised money market funds, France and UK
Stuut — $52.5M Series B led by Insight Partners, AI order-to-cash for enterprises, US
Meanwhile — $37.5M at a $350M valuation, bitcoin-denominated life insurance, Bermuda
Vesta — $30M led by Conversion Capital, with Pennymac, New American Funding, Citi Ventures and a16z, AI agents for mortgage origination, US
Catalyst — $30M seed led by Sequoia Capital, AI trading agents for retail investors, US
TrueLayer — $27M led by CDP Venture Capital, pay by bank network, UK
AblePay Health — $20M Series A led by F-Prime, out-of-pocket medical cost payments, US
Cleavr — €8M seed led by Varsity, automated invoice collection, France
Comparables.ai — $6M seed led by Pragmatech and Araya Ventures, AI M&A intelligence, Finland
PlannerPal — $6M led by Mercia Ventures, AI workflow for financial advice firms, UK
IMMIX — $3.5M from Crane Venture Partners, BTSE and Portfolio Ventures, FX infrastructure for non-dollar stablecoins, UK
TODAY — €2.8M seed co-led by HTGF and Insurtech Gateway, AI sales platform for financial and insurance advisors
simpL — €1.2M pre-seed led by Techshop Capital, AI operating system for B2B sales, Italy
One Trading — strategic investment from Nasdaq Ventures, amount undisclosed, MiFID II derivatives venue, Netherlands
Debt and credit
Settle — $240M credit facility, working capital lending to product businesses, US
MNT-Halan — more than $82M in securitised bond issuances as its loan book approaches $1B, Egypt
Asaas — R$300M (about $55.6M) FIDC, receivables advances for SMEs, Brazil
VC funds
Forbion — €2.3B across Growth Opportunities Fund IV and Ventures Fund VIII, biotech, Netherlands
Endeavor Catalyst — $320M Fund V, oversubscribed against a $300M target, co-investments in Endeavor Entrepreneur companies
SEVA Growth — $160M Fund II, minority growth equity in profitable founder-led software, US
Linse Capital — $150M Ignition strategy, $75M early-stage fund plus $75M co-investment, deep tech, US
Graduate Ventures — €125M second seed fund, €100M committed, Dutch tech startups
PSV Tech — €56M Fund II final close, pre-product-market-fit founders in Denmark, Sweden and Norway
Anorak Ventures — $35M Fund III, aerospace, defence and advanced manufacturing, US
Nevermind — €23.6M first close of NVM Venture Lazio, target €35M, dual-use deep tech, Italy
Market news
Stablecoins, crypto and tokenisation
Samsung Wallet adds cross-border USDC transfers on Solana for 82 million US Galaxy devices
Anchorage Digital acquires Routable, a US payouts platform growing over 100% a year
Standard Chartered plans institutional custody for crypto, stablecoins and tokenised assets in Singapore
M&A, listings and results
Revolut targets a US primary listing for its eventual IPO, CEO Nik Storonsky says
Shares completes the acquisition of banking-as-a-service platform Treezor from Société Générale
Grupo Cibest, the Bancolombia holding, plans to acquire 100% of Colombian fintech PTM
Yapily turns profitable as revenue grows from £6.7M to £16.7M in 2025
Licensing, expansion and products
Brite Payments launches Pay by Bank in the UK after securing an EMI licence from the FCA
Revolut plans to apply for digital bank and e-money licences in the Philippines
Revolut passes 6 million customers in Italy, more than 10% of the market
Revolut starts rolling out unsecured personal loans of £2,000 to £25,000 to UK customers
TBC Uzbekistan launches secured SME loans of up to about $1M
Partnerships and infrastructure
TrueLayer partners with SumUp to power instant bank top-ups in the SumUp App
Mastercard makes offline payments a requirement on all new European cards from February 2027
Regulation and enforcement
American Express is fined $350M by the OCC over anti-money laundering failures, alongside a Federal Reserve enforcement action
ESMA gives EU crypto platforms until 8 January 2027 to exit non-MiCA stablecoins such as USDT
Founders to watch
Companies I’ve been talking with this week that I find interesting
Atoms — automation for mining, construction, food production and heavy transport.
KALYP — tokenization infrastructure for assets between US and EU
FLOWPAY — named as one of the fastest growing fintech company in the world by Sifted
Let me know if you want to have a chat with them, always happy to make an intro.
Raising now
Space for GPs and solo GPs launching funds. Not paid. If you’re raising and want to be listed, message me on LinkedIn.
Parallax Ventures — fintech, LatAm. Raising Fund II. [link] · gennari@parallax.vc
Founder Factor — YC-focused. Just closed investments in YC W26 and is expanding the current vehicle to double down on the batch. [link]
RedFish Capital Partners — private equity, Italian SMEs in growth and mature phases. €200M+ AUM. Raising a new AIF with a soft commitment from the European Investment Fund. redfish.capital · investor.relations@redfish.capital
Nothing here is investment advice.
Events, next 30 days
Money20/20 USA — Las Vegas, 18–21 Oct
MERGE Madrid — Madrid, 27–29 Oct
Hong Kong FinTech Week — Hong Kong, 2–6 Nov
Later: Africa Stablecoin Summit, Johannesburg (12–13 Nov) · Solana Breakpoint, London (15–17 Nov) · Singapore FinTech Festival (18–20 Nov) · Fintech Nerdcon, San Diego (19–20 Nov) · Bitcoin MENA, Abu Dhabi (7–8 Dec) · Abu Dhabi Finance Week (7–10 Dec) · TOKEN2049 Dubai (21–22 Apr 2027) · Money20/20 Asia, Bangkok (27–29 Apr 2027)
Want an event listed or sponsored? DM me.
Previous edition: Weekly update #152