

Builders Fintech Funding Index: 204 (last full week, week of 12 Oct). 33 equity rounds recorded, against a 12-week average of 16. Median disclosed USD round: index 40. Our round coverage expanded in September 2026, so the Index overstates activity until mid-December. Full reading
Tradeweb agreed to buy Trumid for about $1.97B, Pigment raised $250M at a $2.3B valuation, and Whop raised $200M at a $5.1B valuation. Below: McKinsey & Company’s Asset management 2026 (record $151T of assets, 52 cents of cost for every new revenue dollar, concentration in every growth market), the week’s rounds and funds, and three managers raising now.
Builders in Fintech: Episode #54 aired on last week, when my guest was André Silva, co-founder and CEO of Quartz.
All episodes: YouTube · Spotify · Apple Podcasts · Amazon. Founders and VCs who want to come on the show: message me on LinkedIn.
Builders in Fintech Daily: yesterday’s rounds and news, every weekday at 8:00. Subscribe here.
The report: asset management, plenty for the few
McKinsey & Company, Asset management 2026: Plenty for the few? The October 2026 report from the Financial Services Practice on why record assets and resilient flows are accruing to a shrinking group of managers. Here my main takeaways:
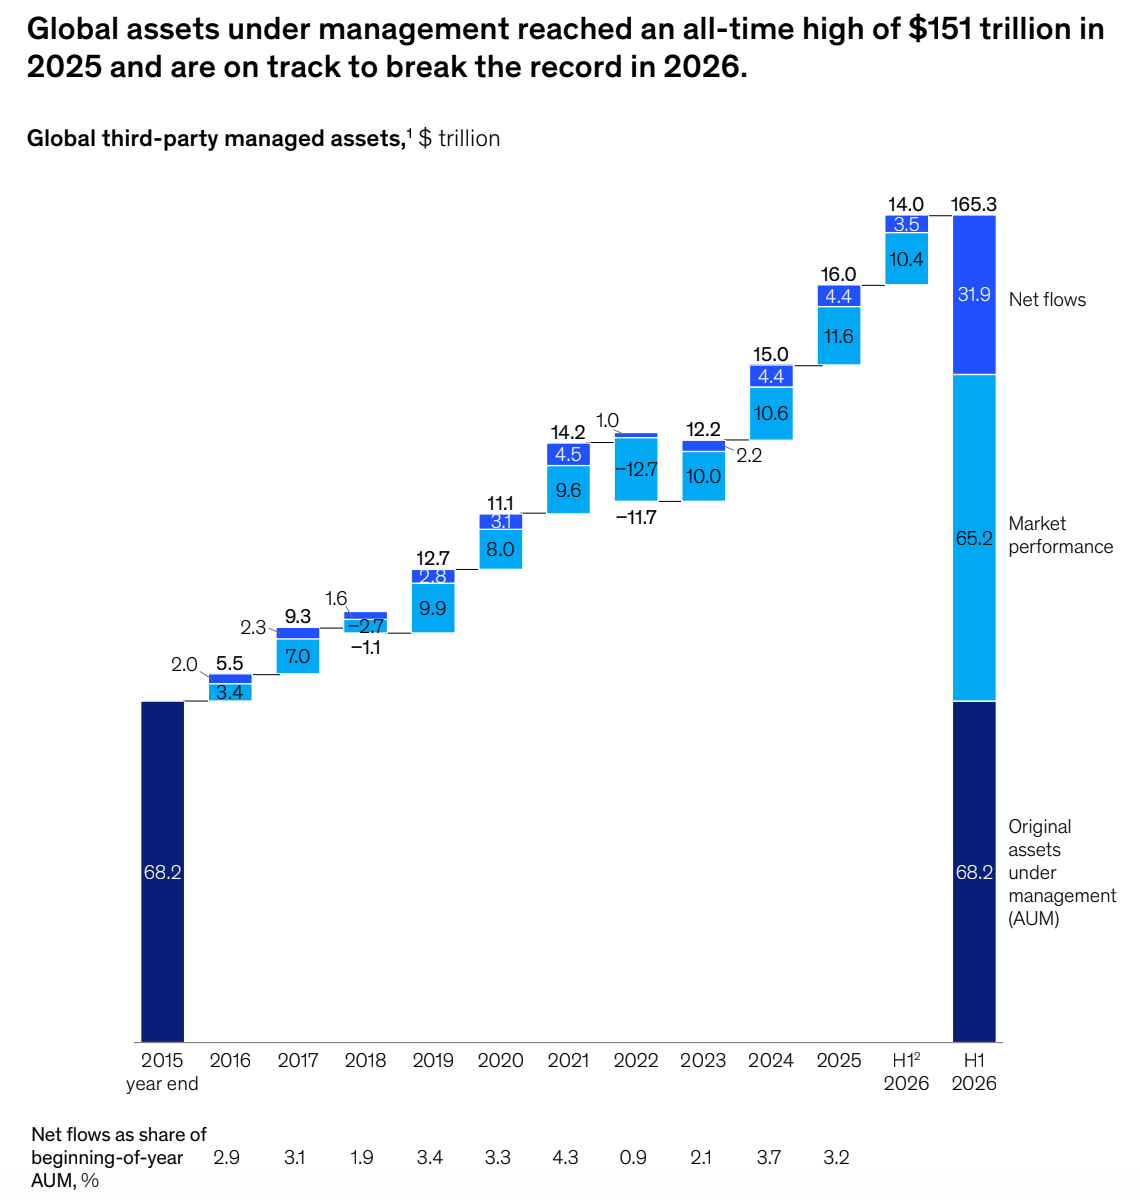
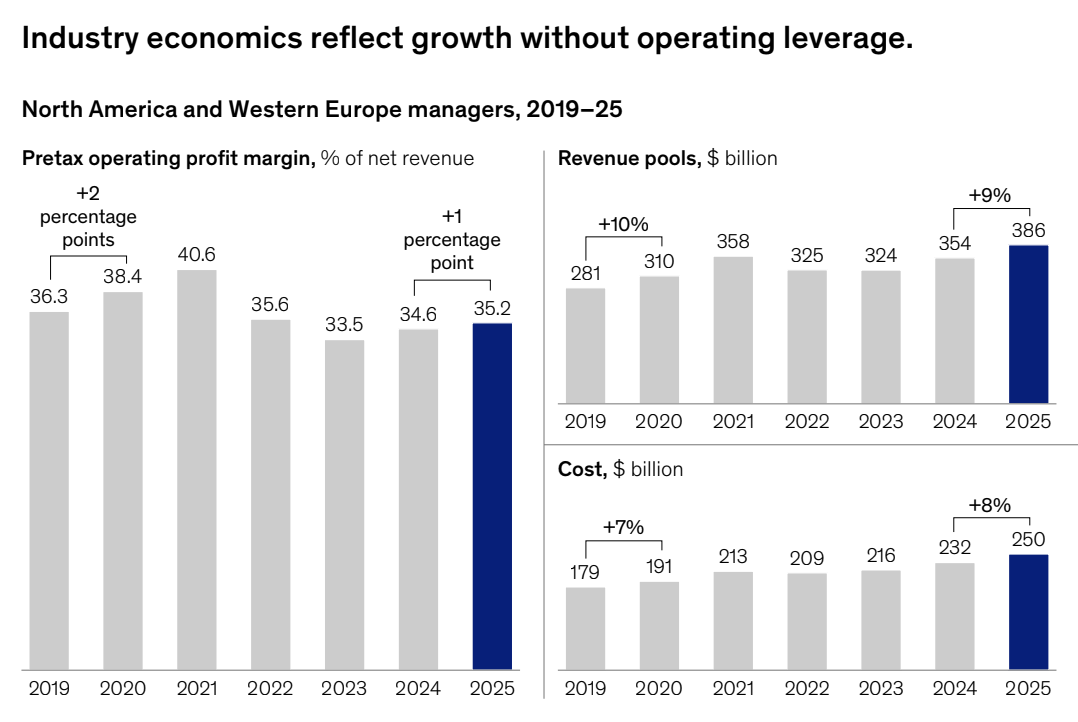
The numbers. Global third-party assets reached a record 151Tattheendof2025(82T in the Americas, $37T in EMEA, $32T in Asia–Pacific) and kept rising in H1 2026. Net flows were 3.2% of opening assets in 2025, inside the 3–4% long-run range; annualising H1 2026 gives close to 5%. Two-thirds of the decade’s growth came from market appreciation, one third from new money. Revenue pools grew about 11% in North America, 9% globally and 4% in Europe in 2025, but costs rose 10% in North America and 3% in Europe, so pretax margins barely moved. The cost base reached about $250B, with technology up 13% to $41B.
The cost of growth. It took 19 cents to earn a new dollar of revenue in 2023 and 52 cents in 2025. Product ranges, wrappers, private-market capability, fragmented distribution and regulation absorb the upside. AI is not yet a dividend: the measurable value sits in software development and technology delivery, while research, distribution and marketing use cases have not reached scale. McKinsey’s phrase is that most managers “have received only the invoice”.
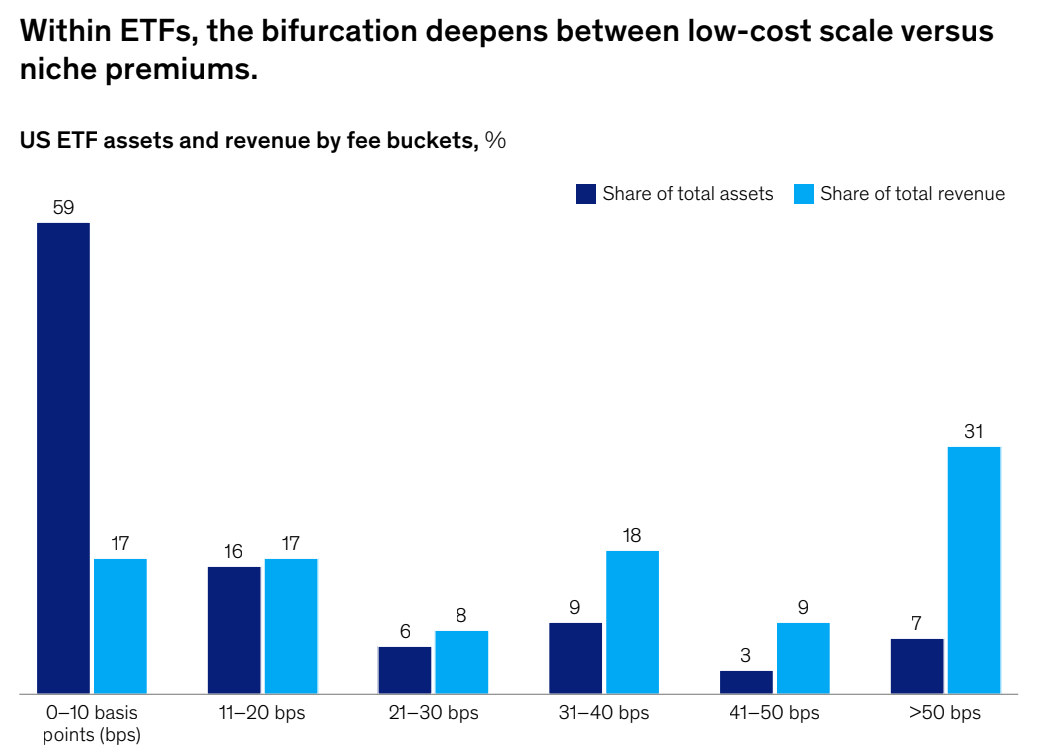
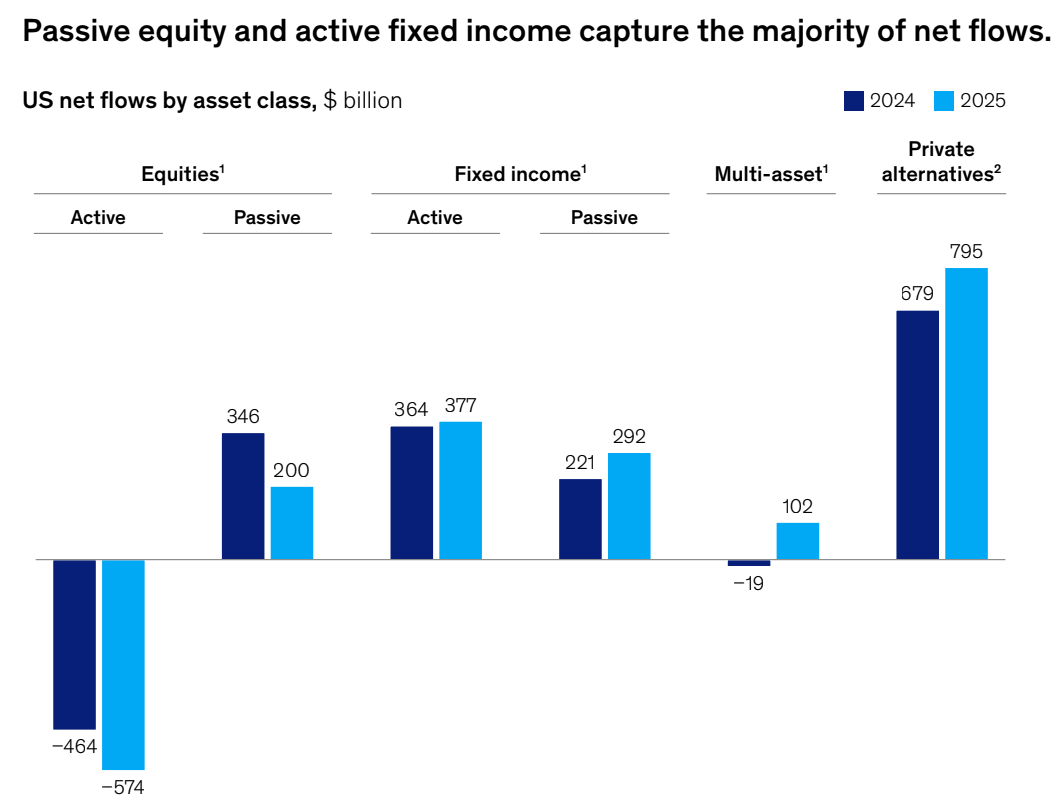
The barbell. Investors buy the cheapest beta and the most sophisticated alpha, and leave the middle. Passive equity and active fixed income take most US flows; active equity keeps losing assets. Global ETF assets are about $22T, and European ETF flows reached about $255B in H1 2026. In US ETFs, products priced at 10 basis points or less hold about 60% of assets and 17% of revenue; products above 50 basis points hold 7% of assets and more than 30% of revenue. Tokenised funds remain small, mostly tokenised cash and money-market products and stablecoin reserves, and the report expects them to deepen concentration rather than disperse it.
Private markets. Closed-end fundraising is still about half a trillion dollars below its peak. McKinsey now expects the digestion of 2021–22 vintage assets to take 12 to 18 months longer than its earlier estimate of two and a half to three years. Retail private credit redemption requests passed $15B in Q2 2026, concentrated in vehicles with software exposure. ELTIF assets nearly tripled in three years to more than $40B at the end of 2025.
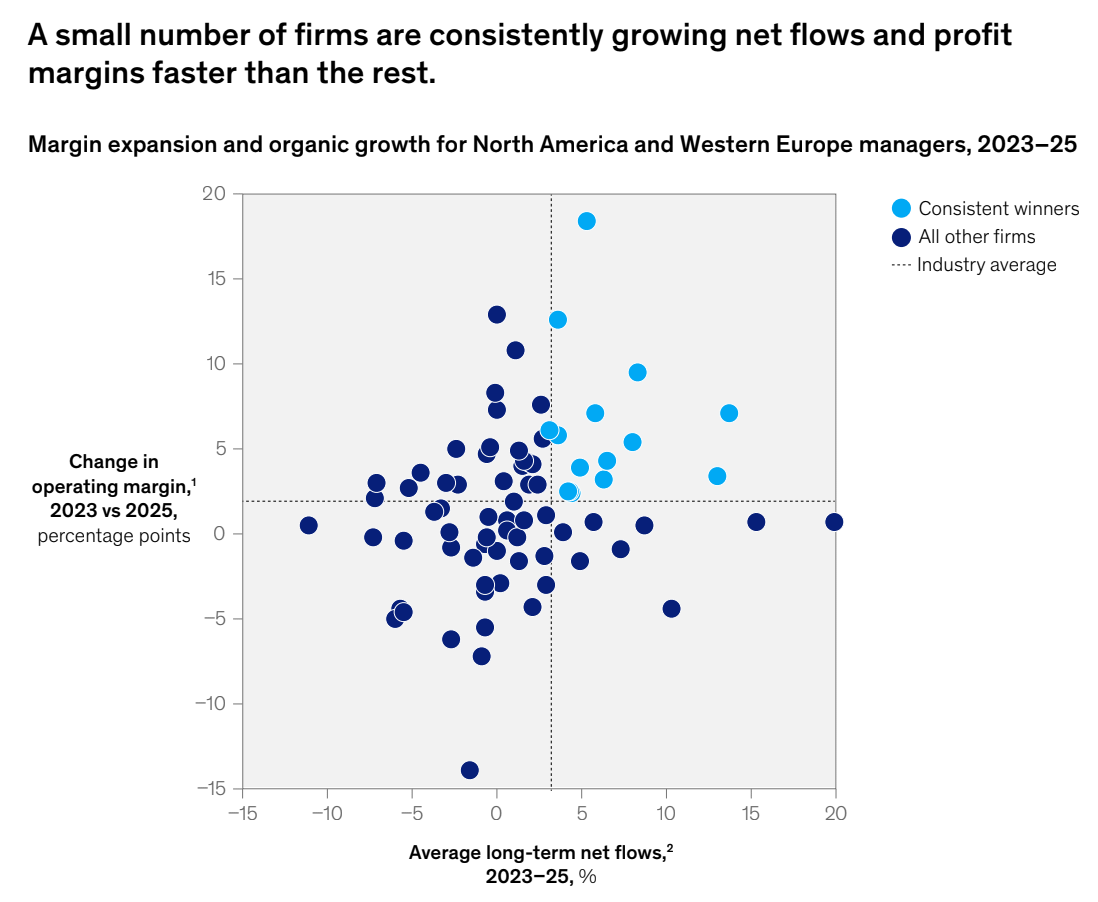
Concentration. The five largest passive ETF managers took 94% of US net flows, up eight points in five years. The ten largest closed-end private credit managers took 72% of fundraising, from 44%; in private equity the top ten took 32%, from 17%. The five largest managers captured 61% of new US retail inflows, from 51%. The report names five forces: clients consolidating relationships, portfolios built around outcomes, control points such as model portfolios and outsourced CIOs, access as a source of alpha, and technology that compounds scale.
The read. The number that matters is 52 cents: what it now costs an asset manager to earn a new dollar of revenue, against 19 cents two years ago. Growth is plentiful and operating leverage is not, and the report’s answer is scale or a distinct edge, with the middle the least defensible ground. This week’s deals follow the same logic. Tradeweb pays $1.97B for Trumid to add credit protocols to its platform, Standard Chartered is buying Zodia Custody to put digital assets next to securities, and capital keeps pooling in funds, with Vintage at $920M and Seaya Nova at €600M while Pear VC raised $333M against $432M for Fund IV. Exposed: mid-sized active managers without a distribution control point or an origination edge. Better placed: ETF platforms, mega-alternatives and anyone who owns the client relationship. Watch whether tokenised funds, which the report says favour incumbents, follow that pattern once the first custody deals close.
The week in six stories
Tradeweb agrees to acquire Trumid for about $1.97B. The price is $1.75B for the business plus about $220M of tax assets, subject to customary adjustments. Trumid runs an electronic marketplace for corporate bonds; the deal moves Tradeweb earlier in the bond lifecycle, into new-issue and grey-market trading. Closing is expected in the first half of 2027.
Mynt lists in Manila after the largest IPO in Philippine history. The GCash owner priced at P6.60 a share, a 34% discount to the P10 maximum, and began trading on 20 October with a market capitalisation of about P442B, around $7B. The offer is about P53B, rising to about P60.9B with the over-allotment option, or roughly $965M [verify: J.P. Morgan puts the full offer at about $970M].
Pigment raises a $250M Series E at a $2.3B valuation. The Scaleup Europe Fund, managed by EQT, led; WIL, Greenoaks, ICONIQ, IVP and Meritech joined, with a planned investment from NVIDIA. The Paris company says annual recurring revenue passed $100M earlier this year, having doubled; its last round was a $145M Series D in 2024.
Whop raises a $200M Series D at a $5.1B valuation. Sequoia and Shopify Ventures led, and Sequoia’s Doug Leone joins the board. The round follows a $200M Tether investment at $1.6B in February; the company says about 25,000 operators generate $550M a month on its platform. Dealroom reports the round at $205M; the company release says $200M.
Stand raises a $70M Series C at a $1B valuation led by Saga Ventures. Lowercarbon, Eclipse, Equal Ventures, Inspired Capital, Neotribe and Jackson Square Ventures took part, bringing total funding to about $130M. The value of property the home insurer covers grew from about $1B to more than $10B in a year. The round was announced on 15 October.
Standard Chartered signs definitive agreements to acquire Zodia Custody. The bank buys 100% of Zodia Custody Limited, which holds regulated entities in Singapore, Hong Kong, Australia, the UAE and Luxembourg; terms were not disclosed and completion needs regulatory approvals. Custody moves into Securities Services, and Zodia’s software business goes to Zodia Solutions under SC Ventures.
Also: Legora raises a $550M Series E at an $8.8B valuation; Plata crosses $1B in annual recurring revenue with 4M customers; Ramp applies to the OCC for a national trust bank charter days after its $60B valuation; JPMorgan puts its JPM Coin deposit token on Ethereum mainnet; Dougs raises €50M from Expedition Growth Capital for agentic accounting; Hyperlayer raises £19.5M at a £195M valuation; Wise lifts its full-year outlook after Q2 net revenue grew 21% to $739.1M; Bain Capital commits up to $250M to FundPark.
Funds. Eleven new vehicles this week: Vintage Investment Partners (920Mraisedinnewfunds),Seaya(€600MfirstcloseofSeayaNova,SeriesBtoDinEuropeantech),InspiredCapital(450M Fund IV), Pear VC ($333M Fund V, down from 432M),BisonVentures(160M Fund II, early-stage AI for the physical world), The FSE Group (£70M+ debt fund for London scale-ups, with the British Business Bank), Nauta Capital (€60M first close of Fund VI), Turbine Capital (€54M debut fund for Nordic deeptech), Enzo Ventures (€20M Fund II for Southern European founders), BackingMinds (€20M commitment from the European Investment Fund to Invest III) and Masia (€18M debut fund in Barcelona).
All rounds
Equity
Dougs — €50M from Expedition Growth Capital, agentic accounting, France
Coast — $35M growth equity led by Thomvest Ventures, financial platform for field businesses, US
Rebill — $5.4M pre-Series A, payments across the Americas without local entities, Argentina
Zaria — $5.2M seed led by Lightspeed, loan servicing and trustee infrastructure for structured finance, US
RedOwl — A$5.3M seed led by Tidal Ventures, AI that finds margin leakage in invoices and spend, Australia
Rulen — €1.8M led by VC Partners, agentic AI workflows for Italian tax and accounting firms, Italy
Debt and credit
FundPark — up to $250M from Bain Capital, working capital for e-commerce SMEs, Hong Kong
VIVA Finance — $150M credit facility with Viola Credit, payroll-linked personal loans, US
Bold — COP 37.45B (about $11.3M) loan from BBVA Spark, lending to merchants, Colombia
VC funds
Seaya — €600M first close of Seaya Nova, growth fund for Series B to D rounds in European tech
Pear VC — $333M Fund V, down from $432M for Fund IV, three partners promoted to GP, US
Bison Ventures — $160M Fund II, early-stage AI for the physical world, US
The FSE Group — £70M+ Future London Growth Fund, debt fund for scale-ups with the British Business Bank and Funding London
Nauta Capital — €60M first close of Fund VI, anchored by the British Business Bank, B2B software
BackingMinds — €20M commitment from the European Investment Fund to Invest III, Nordic early stage
Masia — €18M debut fund, early-stage AI and frontier tech, Barcelona
Market news
Stablecoins, crypto and tokenisation
Nubank launches Nu Global, fee-free transfers across 35+ countries on stablecoin rails
StraitsX partners with Visa to take its stablecoin-backed card issuing beyond Asia to more than 100 markets
M&A and capital markets
Standard Chartered signs definitive agreements to acquire Zodia Custody
MNT-Halan closes up 6.6% on its first day in Cairo after Egypt’s biggest IPO since 2021, valuing the Egyptian business at about $770M
Acorns acquires Frich, a 1.6M-member community where young Americans learn about money from each other
Licensing and regulation
Deutsche Bank plans to launch crypto custody in Germany within weeks and take it to Asia in 2027
Ant International secures UAE payment and stored value licences, clearing the way for Antom acquiring and WorldFirst accounts
Central Bank of Ireland fines Coinbase Ireland €3.25M over safeguarding and outsourcing failures
Revolut receives an S&P Global Ratings action
Growth, products and partnerships
Checkout.com moves into in-person payments, with Mollie as launch partner
Airwallex renews its McLaren Racing Formula 1 partnership as AI finance partner
LemFi launches savings, credit and eSIM in its biggest product expansion
Zilch is moving to a new office and doubling headcount in London
Onafriq winds down Baxi, its Nigerian agent banking business, five years after buying it
On the platform
Companies raising and products listed on Builders in Fintech this week.
Raising now on the platform
Out of It, Inc. — accounting for SMBs and accounting firms: books, bank feeds, invoicing, practice management and a marketplace in one login. Seed, United States, raising $500K.
OVRUM Pay — lets small businesses sell, accept payments and access their money faster from an iPhone. Pre-seed, United States, raising $200K.
Listings are provided by the companies, not verified, and not an offer. Raising? Get listed at buildersinfintech.ai/raising.
Products
Business cards by Coast — fuel, fleet and field expense cards for trade businesses; the company raised $35M this week.
FX payments by Mesh — crypto payments network connecting 300+ wallets and exchanges through one API; it is in the news this week with Visa.
Raising now
Space for GPs and solo GPs launching funds. Not paid. If you’re raising and want to be listed, message me on LinkedIn.
Parallax Ventures — fintech, LatAm. Raising Fund II. [link] · gennari@parallax.vc
Founder Factor — YC-focused. Just closed investments in YC W26 and is expanding the current vehicle to double down on the batch. [link]
RedFish Capital Partners — private equity, Italian SMEs in growth and mature phases. €200M+ AUM. Raising a new AIF with a soft commitment from the European Investment Fund. redfish.capital · investor.relations@redfish.capital
Nothing here is investment advice.
Events, next 30 days
MERGE Madrid — Madrid, 27–29 Oct
Hong Kong FinTech Week — Hong Kong, 2–6 Nov
Africa Stablecoin Summit — Johannesburg, 12–13 Nov
Solana Breakpoint — London, 15–17 Nov
Singapore FinTech Festival — Singapore, 18–20 Nov
Fintech Nerdcon — San Diego, 19–20 Nov
Later: Bitcoin MENA, Abu Dhabi (7–8 Dec) · Abu Dhabi Finance Week (7–10 Dec) · TOKEN2049 Dubai (21–22 Apr 2027) · Money20/20 Asia, Bangkok (27–29 Apr 2027)
Want an event listed or sponsored? DM me.
Previous edition: Weekly update #154