

Welcome to this edition of the weekly newsletter. The idea behind this is to gather all the information in the startup ecosystem in one place, with a special focus on the fintech market and the VC industry.
The Builders podcast will be back next week with another interesting guest. In the meanwhile, you can recover the last episode with Ertan Can , founder of Multiple Capital, with the full video here on YouTube, and the audio here on Spotify and here on Apple Podcast.
It's a unique perspective on how an investor decides on which funds to invest, and consequently on how VC managers drive their decision process. With Ertan, we will discuss the VC industry in Europe, on how to choose a fund, and what the European startup ecosystem is missing to catch up the gap with the US.
Coming back to us, I am recently deep diving on the Indian startup ecosystem, one of the most interesting emerging markets for fintech and startups overall. This week, I was reading the “India Venture Capital report 2024” by Bain & Company, a comprehensive study on the VC activity in the country in 2024. Here my main takeaways:
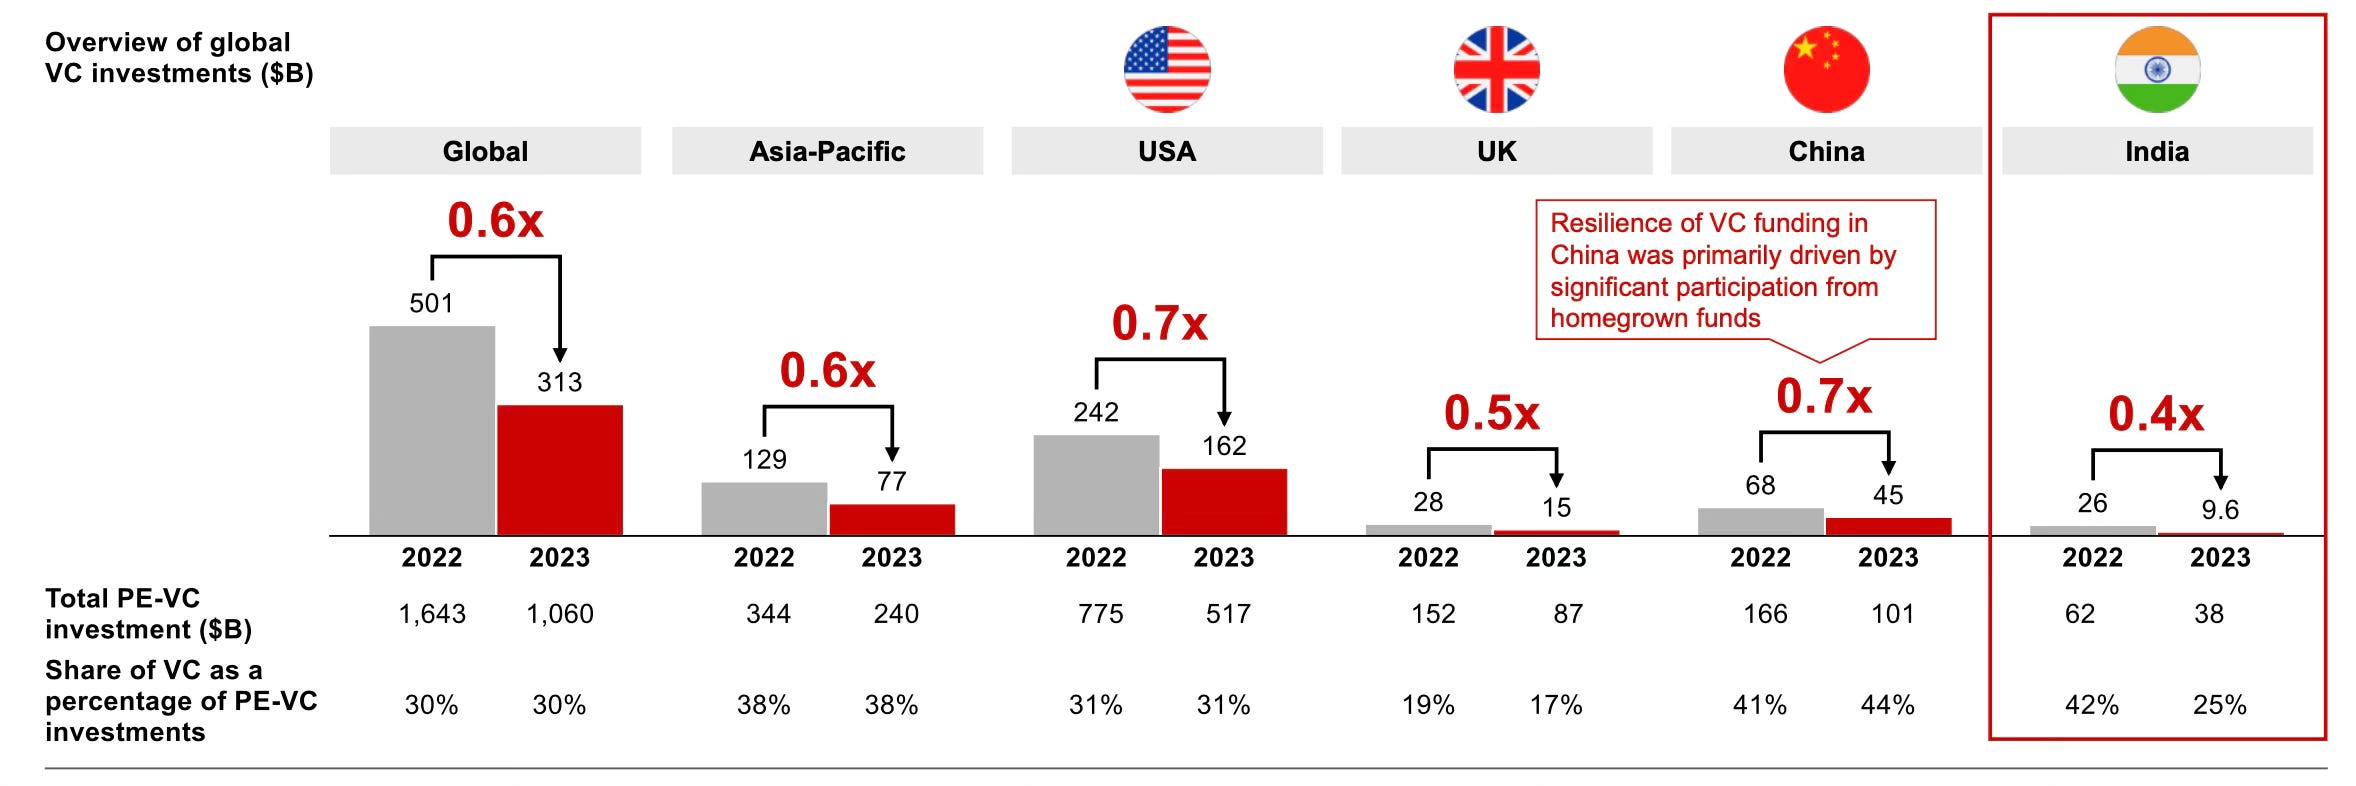
The global venture capital (VC) landscape experienced a significant decline in deal activity during 2023, with VC funding in India shrinking to approximately 40% of its 2022 levels.
While global VC investments dropped to 60% of the previous year, India saw an even sharper contraction, marked by a ~45% reduction in deal volume (from 1,600 deals in 2022 to 880 in 2023) and a ~30% decrease in average deal value (from $16 million to $11 million).
India’s prominence in the Asia-Pacific VC landscape also waned. After achieving its highest share of regional funding in 2022, India’s share fell from ~20% to ~12% in 2023, though it maintained its position as the second-largest VC market in the region. Meanwhile, countries like China and Japan gained ground, with China demonstrating resilience due to strong participation from local funds.
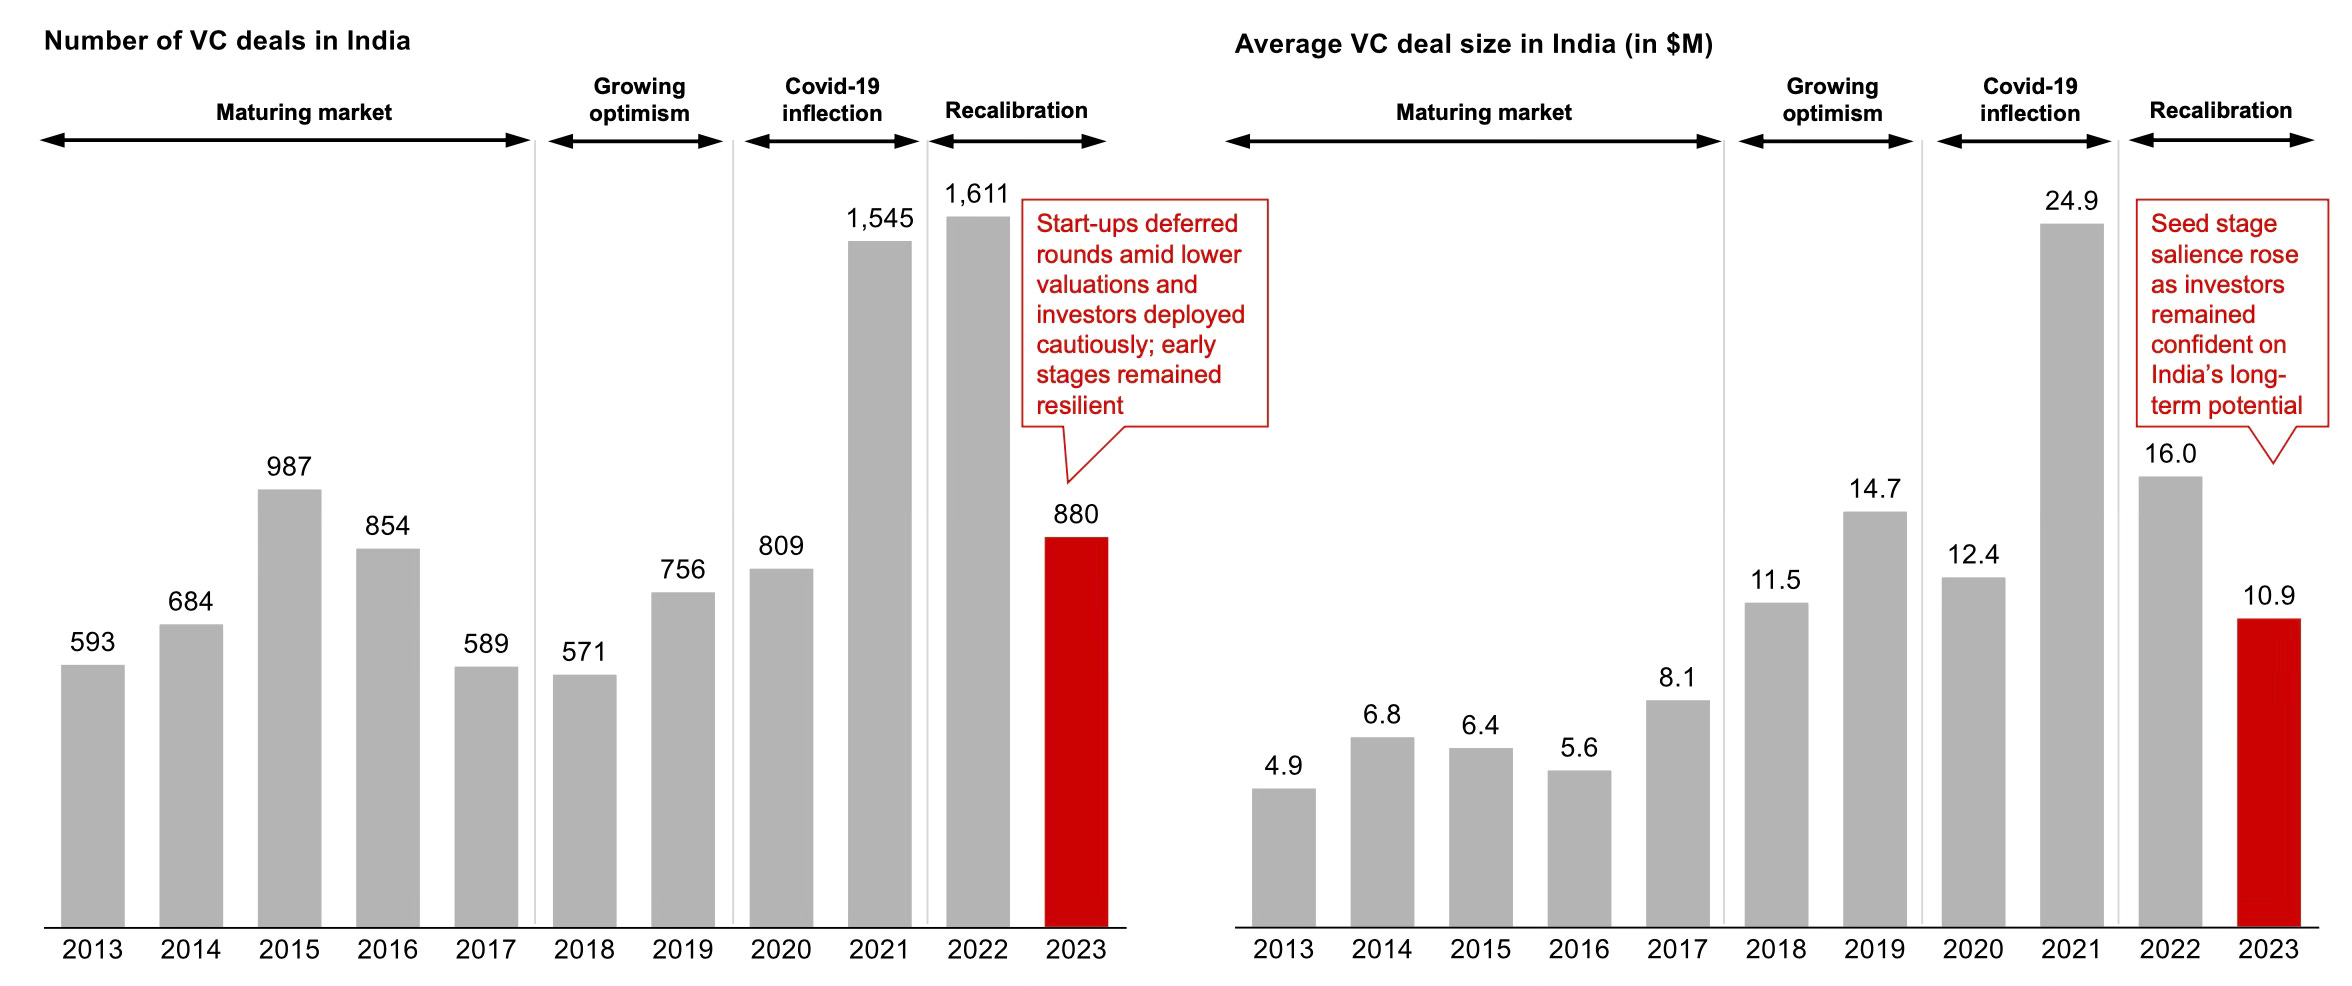
India's startup ecosystem has undergone notable evolution, marked by growing optimism and investor interest in first-generation startups. Global hedge funds such as Tiger Global and SoftBank, along with prominent VCs, have scaled their presence in the Indian market, signaling confidence in its potential. However, investor caution began to surface in 2016–17 due to uncertainties surrounding exits for earlier investments.
While the pandemic initially tempered investor activity, a resurgence of confidence in 2021 led to record investments, driven by ecosystem growth and marquee exits. Sectors like fintech, software, and SaaS gained traction, attracting increased attention from investors. However, macroeconomic challenges in 2022–23 prompted a recalibration of investment strategies, compressing valuations and prolonging the funding winter, which impacted both deal volumes and average deal sizes.
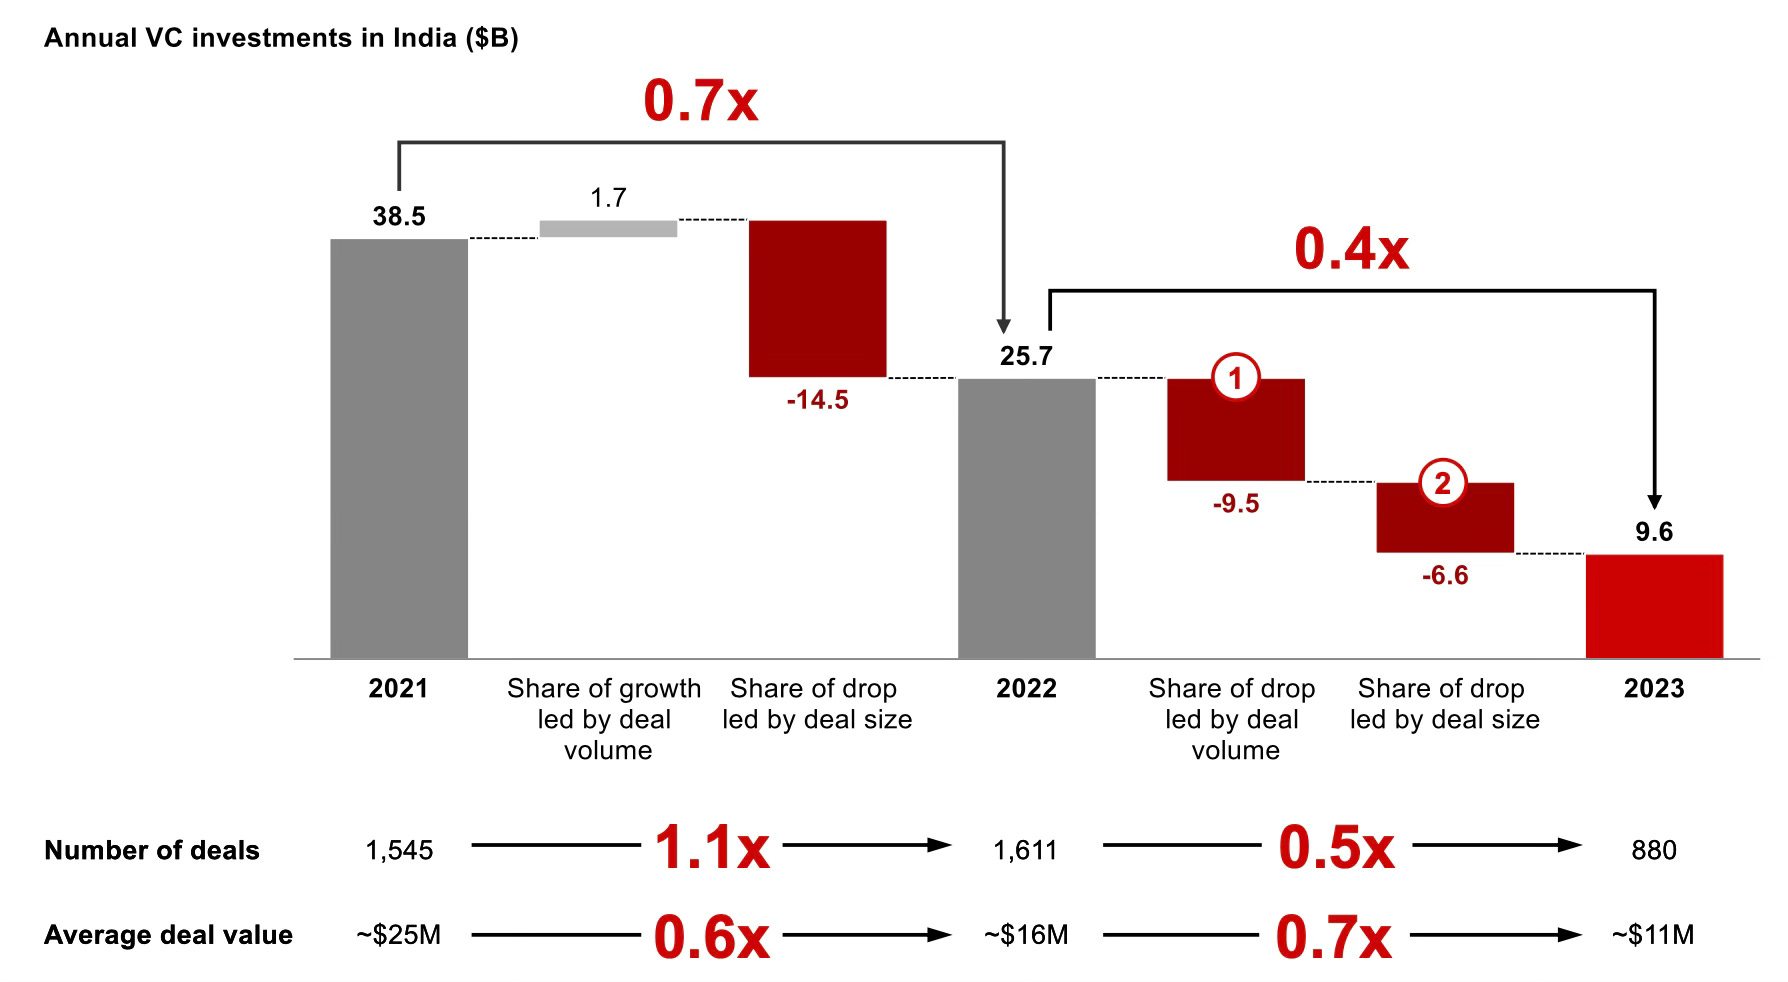
Macroeconomic challenges and compressed valuations prompted startups to delay funding rounds, with investors focusing on long-term opportunities through early-stage deals.
In a cautious investment climate, startups prioritized extending their runway, deferring fundraising efforts in a valuation-constrained environment. Simultaneously, investors exercised restraint in deploying capital, leading to muted deal volumes.
While overall deal activity declined, early-stage investments gained prominence. Seed-stage deals accounted for approximately 70% of the total volume in 2023, up from ~60% in 2022. This trend was driven by investor confidence in India's long-term growth potential, a robust supply of pre-seed and seed-stage startups, and sustained participation in these segments.
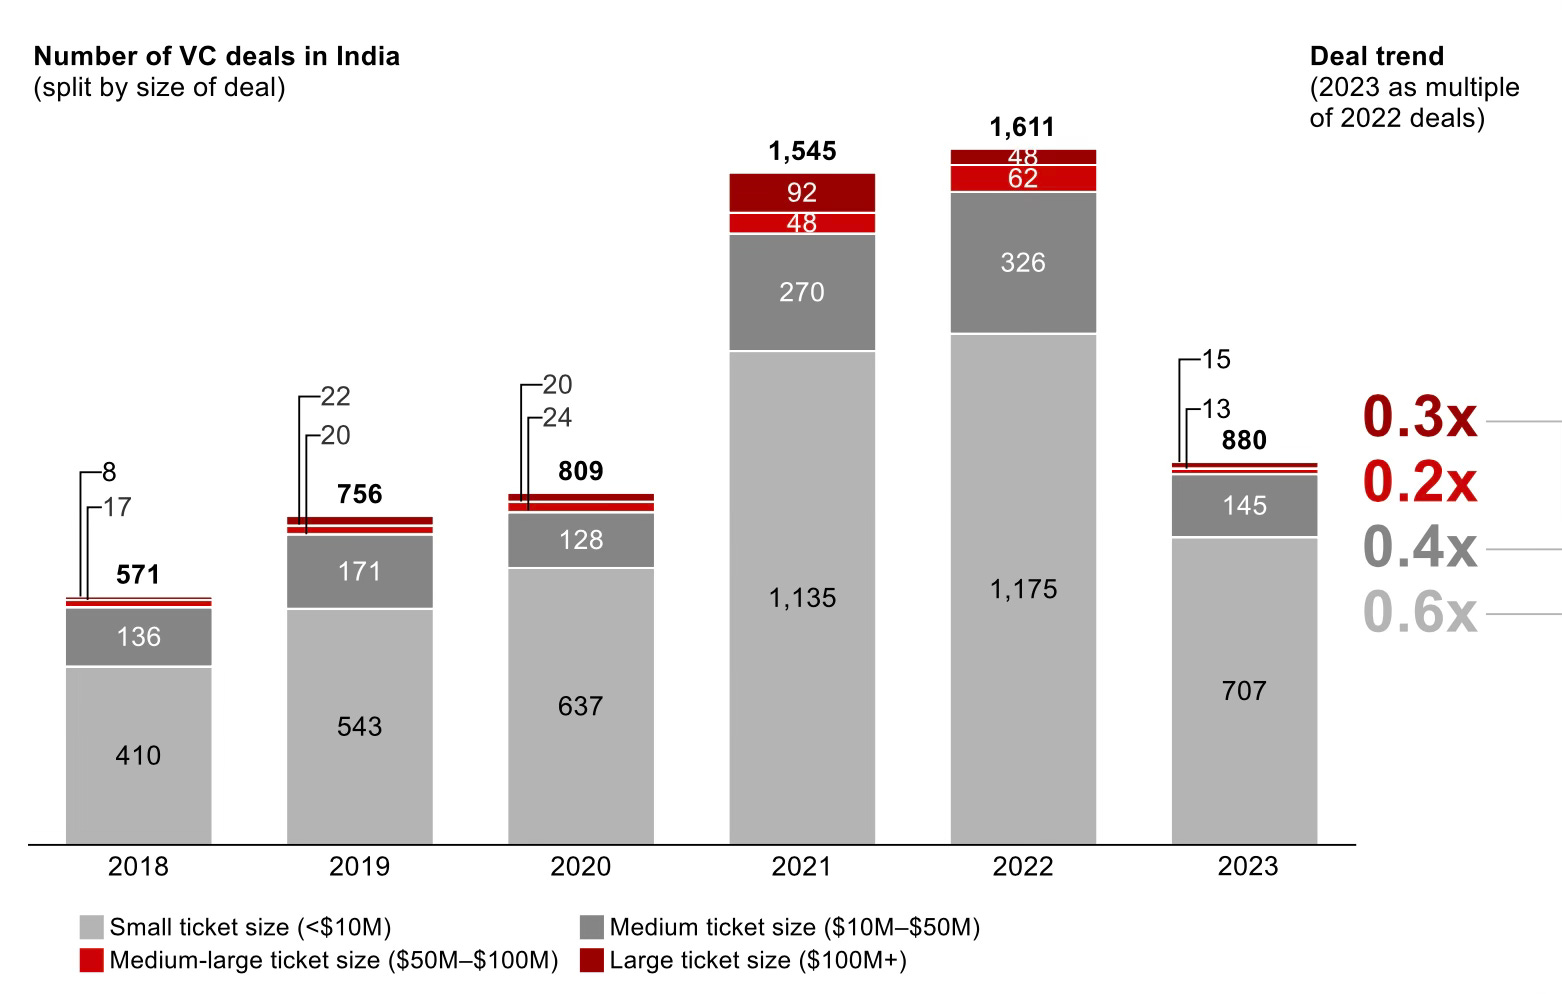
Deal activity slowed across all investment sizes in 2023, with mega-rounds ($100M+) experiencing the sharpest decline, reaching their lowest levels since 2019 with only 15 deals exceeding $100 million.
General Partners (GPs) adopted a cautious approach as economic uncertainties tempered return expectations. Simultaneously, startups sought to secure better valuations by delaying fundraising and focusing on extending their financial runway.
Smaller and mid-sized deals (<$50M) exhibited relatively less decline compared to mega-rounds, supported by optimism surrounding India’s medium- to long-term growth prospects. Additionally, emerging sectors such as electric mobility and generative AI attracted growing investor interest, providing some resilience to the overall deal momentum.
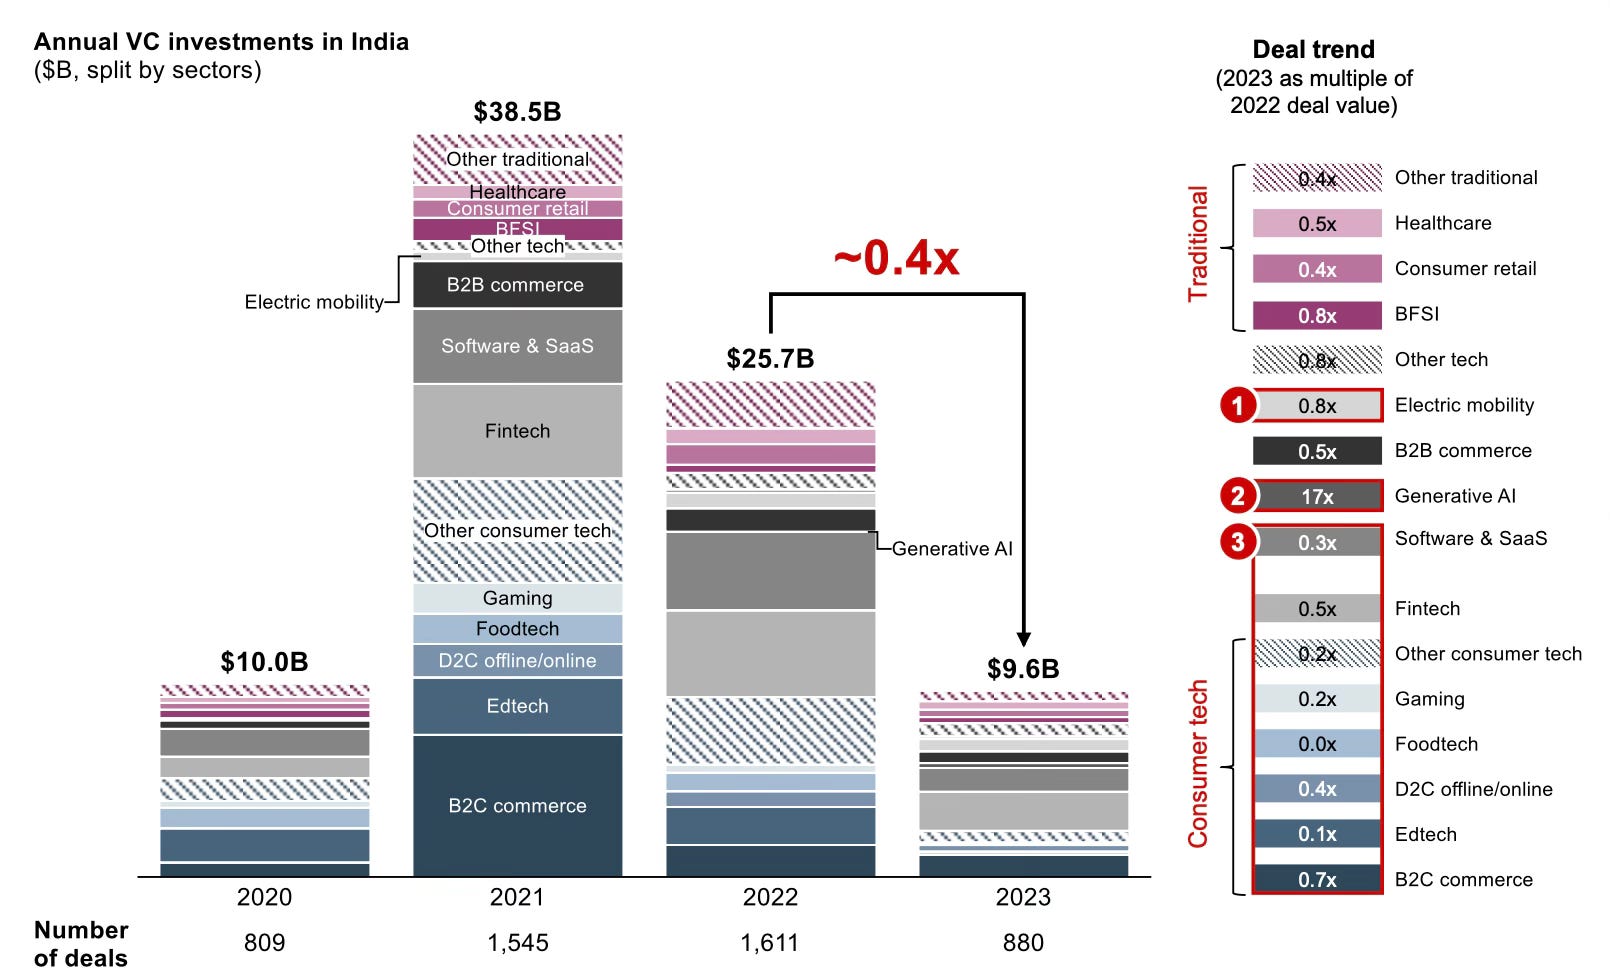
Key technology sectors remained prominent but experienced a decline in activity, with a noticeable shift toward traditional sectors and emerging themes.
Electric mobility, a green-shoot sector from 2022, showed resilience with 44 deals spanning the value chain. Major recipients included OEMs like Ola Electric and Ather, as well as mobility services such as BluSmart and Zypp Electric, which together secured ~70% of the funding.
Generative AI emerged as a standout theme, with deals increasing from fewer than 5 in 2022 to 17 in 2023. Funding was primarily directed at applications (~80%) over infrastructure (~20%), as companies demonstrated early signs of product-market fit, particularly in areas like marketing, support, and legal services.
Tech-first sectors like fintech, consumer tech, and software & SaaS faced a sharp decline, with funding dropping to 30% of 2022 levels. The number of large-ticket ($100M+) deals fell significantly, from 35 in 2022 to just 10 in 2023, reflecting tempered investor enthusiasm.
Anyway we saw some very interesting news in the market this week. eToro is filing for an IPO in the US, and it’s not the only one as Mistral AI is reported working for the same target. Revolut released an anti-impersonation scam feature, Google Pay is lending in Saudi Arabia and OpenAI announced the $500 billion stargate project, while Checkout.com reported a full year of profitability in 2024. In the VC industry, FTV Capital raised $4.05 billion for new funds, while Sigma Capital raised a $100 million fund and Outsiders Fund a $150 million fund. In the italian market, fintech startup Qomodo raised a $13.5 million series A and FunniFin - Financial Wellbeing a $850k pre-seed, while Banca Monte dei Paschi di Siena made a first offer to buy Mediobanca. And finally, some very interesting funding rounds from fintech startups like Phantom, Karmen, Nilus, Waza (YC W23), Tapline, Vertice, Crescenta and many others.
But let's take a closer look at the main news of the last seven days.
Closed deals
Crypto wallet Phantom raises a $150 million series C led by Sequoia Capital
AI-powered treasury solution Nilus raises a $10 million funding round
London based fintech Fundment raises $53 million for its all in on tech platform
French fintech Karmen raises $9.4 million for its revenue-based financing platform
Waza (YC W23) launches Lync, backed by $8M, to revolutionize banking for African startups
Sydecar raises $11M Series A to simplify private market transactions
Climate fintech Bees & Bears GmbH raises a $500 million round
Smart Data Foundry raises $3 million to revolutionize UK financial research
Egypt based fintech MoneyHash secures $5.2 million to provide a single entry point to payments in MENA
Tapline secures €20M Pre-Series A to transform SaaS financing in Europe
Card issuance platform Highnote secures $90M Series B to expand into merchant acquiring
Vertice secures $50M Series C to transform SaaS spend optimization
Spanish fintech Crescenta closes a $7 million round to innovate private equity fund management
Employee fintech Aslan has secured a $5 million seed round
UK based fintech Keyless secures a $2 million round to fuel North America expansion
Sweden based Open Payments open banking platform raises a €3 million funding round
Method raises a $41.5 million Series B round
Insights on the VC industry
Scrum Ventures raises a fifth fund at $68 million to invest in sport and entertainment
33East launches a €26M fund to transform Cyprus into a Tech and Innovation Hub
San Francisco based Caffeinated Capital is aiming to raise $500 million for its fifth fund
Outsiders Fund is raising a third $150 million fund
News on the market
Trading platform eToro files for US IPO and is looking for a $5 billion valuation
Google is going to launch its main fintech service, Google Pay, in Saudi Arabia in 2025
Oui Capital was able to return its $4 million debut fund thanks to the sales of shares from Moniepoint Group
Revolut release a feature to identify impersonation scams with in-app calls
Mistral AI is working to prepare an IPO, as the founder recently confirmed to Bloomberg
Stripe reduces workforce by 300 amid strategic restructuring
Indian fintech Jar reaches profitability for the first time and start talks for a $50 million round
OpenAI announces the Stargate Project: $500B investment to revolutionize AI infrastructure in the U.S.
Checkout.com achieves 45% growth and returns to profitability in 2024
A special look in the Italian market
Qomodo raises a 13,5 million series A to reshape payments in physical stores in Italy
FunniFin - Financial Wellbeing raises 850k euro to introduce financial education as a benefit for employees
Breaking news sul mercato bancario italiano: Banca Monte dei Paschi di Siena proposed a first not agreed acquisition offer to buy Mediobanca
And here some useful resources for everyone involved in the ecosystem:
Events you don’t want to miss
DXPX - Munich | 26-27.01.2025 (Link to the event)
TechChill - Riga (Latvia) | 5-7.02.2025 (Link to the event)
0100 DACH - Wien (Austria) | 18-20.02.2025 (Link to the event)
Tech Arena - Stockholm (Sweden) | 20-21.02.2025 (Link to the event)
You have a cool event you want to mention or to sponsor? Feel free to send me a DM.
Startups raising funds
Loyyal - Loyalty platform from the MENA region, with entities in the US and South East Asia, provides a B2B2C platform to handle multiple loyalty programs and earn rewards all over the world. Raising a $6M Series A
Freedhome - Proptech and fintech platform, enabling people to be able to gain profit from real estate by renting them to intermediaries. Raising a $1M seed round
Tutornow - Edtech that provides an online tutoring platform for students with learning disorders. Raising $500k to $1M.
Weagle - B2B Tech startup that provides the very first browser designed for company, with total security for sensitive data. Raising $6 millions for their seed round.
Shoppy Code:Gift card platform that offers a points based loyalty program. They share part of the profits coming from marketing budgets with their customers. Raising $500k.
Take also a look at the last edition of the newsletter, Weekly update #64